Imagine trying to open a bank account, but instead of handing over your passport and utility bill to a teller, you prove you’re human-and not on a sanctions list-without revealing your name. That’s the promise of modern DeFi compliance. It sounds like science fiction, but in 2026, it’s becoming a technical reality. The tension between traditional financial rules and blockchain’s permissionless nature has created a messy middle ground. You want privacy; regulators want visibility. How do you satisfy both without killing the innovation that made Decentralized Finance (DeFi) popular in the first place?
The core problem is simple: Know Your Customer (KYC) rules were written for banks with physical branches, not smart contracts running on Ethereum or Solana. Yet, as institutional money floods into DeFi, the "wild west" days are ending. According to a March 2025 report by Chainalysis, 62% of institutional investors now demand KYC-compliant solutions before they touch a protocol. If you’re a developer, investor, or regular user, understanding the shift from rigid identity checks to flexible, privacy-preserving verification is no longer optional-it’s essential for survival in this market.
Why Traditional KYC Clashes with DeFi
Traditional KYC relies on centralized data storage. You upload a photo of your ID to a company, they store it, and hope they don’t get hacked. In DeFi, there’s often no central entity to hold that data. When the Financial Action Task Force (FATF) issued its guidance in June 2019 requiring Virtual Asset Service Providers (VASPs) to implement KYC, it assumed a middleman existed. For many pure DeFi protocols, that assumption fails.
This mismatch creates friction. Users in regions with unstable banking systems, like Venezuela or Nigeria, often find traditional KYC platforms inaccessible due to poor documentation options or slow processing times. A Koinly survey revealed that 78% of users on no-KYC platforms come from countries with limited banking infrastructure. For them, mandatory ID checks aren’t just annoying-they’re barriers to entry. Meanwhile, regulators worry about money laundering across borders. The solution isn’t choosing one side; it’s building bridges that respect both needs.
The Rise of Zero-Knowledge Proofs and Privacy Tech
If you’ve heard of zero-knowledge proofs (ZKPs), you might think they’re too complex for everyday use. Think again. ZKPs allow one party to prove to another that a statement is true without revealing any information beyond the validity of the statement itself. In plain English: you can prove you’re over 18 without showing your birthdate, or prove you’re not on a sanctions list without revealing your name.
This technology is reshaping compliance. Instead of dumping personal data into a database, protocols use cryptographic methods to verify eligibility. Dr. Garrick Hileman, Head of Research at Blockchain.com, noted in early 2025 that the debate between full anonymity and full surveillance is false. We are seeing a middle path emerge. For instance, the World Economic Forum launched the Decentralized Identity Alliance in April 2025, bringing together 37 projects to standardize these privacy-preserving KYC solutions.
| Feature | Traditional KYC | No-KYC Protocols | ZK-Proof Compliance |
|---|---|---|---|
| Data Exposure | High (Name, Address, ID) | None | Minimal (Cryptographic Proof) |
| Regulatory Acceptance | Standard | Low/Restricted | Growing (EU MiCA aligned) |
| User Friction | High (Days/Weeks) | Low (Instant) | Medium (Setup required) |
| Institutional Access | Full | Limited | Increasing |
Key Players and Their Strategies
The landscape is dominated by two types of actors: centralized compliance providers and decentralized protocol builders. On the centralized side, companies like Chainalysis and Elliptic provide the heavy lifting for risk screening. They track transactions across 45+ blockchains, flagging suspicious activity. But their services are expensive, ranging from $25,000 to $500,000 annually, which puts them out of reach for smaller protocols.
On the decentralized side, we see innovative workarounds. Take TrueFi, an uncollateralized lending protocol that uses reputation-based verification instead of traditional KYC. Or look at Robosats, a peer-to-peer Bitcoin exchange using the Lightning Network. Robosats processes about $42 million monthly without asking for IDs, though it caps trades at $1,400 to manage risk. This approach works well for retail users but struggles with large institutional flows.
Then there are hybrid models. Uniswap, the giant of decentralized exchanges, recently integrated with Circle’s identity verification system. This allows users to opt-in for fiat on-ramps while keeping the core swap functionality permissionless. It’s a clever compromise: if you want to move dollars easily, you verify; if you’re swapping ETH for USDC, you stay anonymous.
Regional Regulations and Global Standards
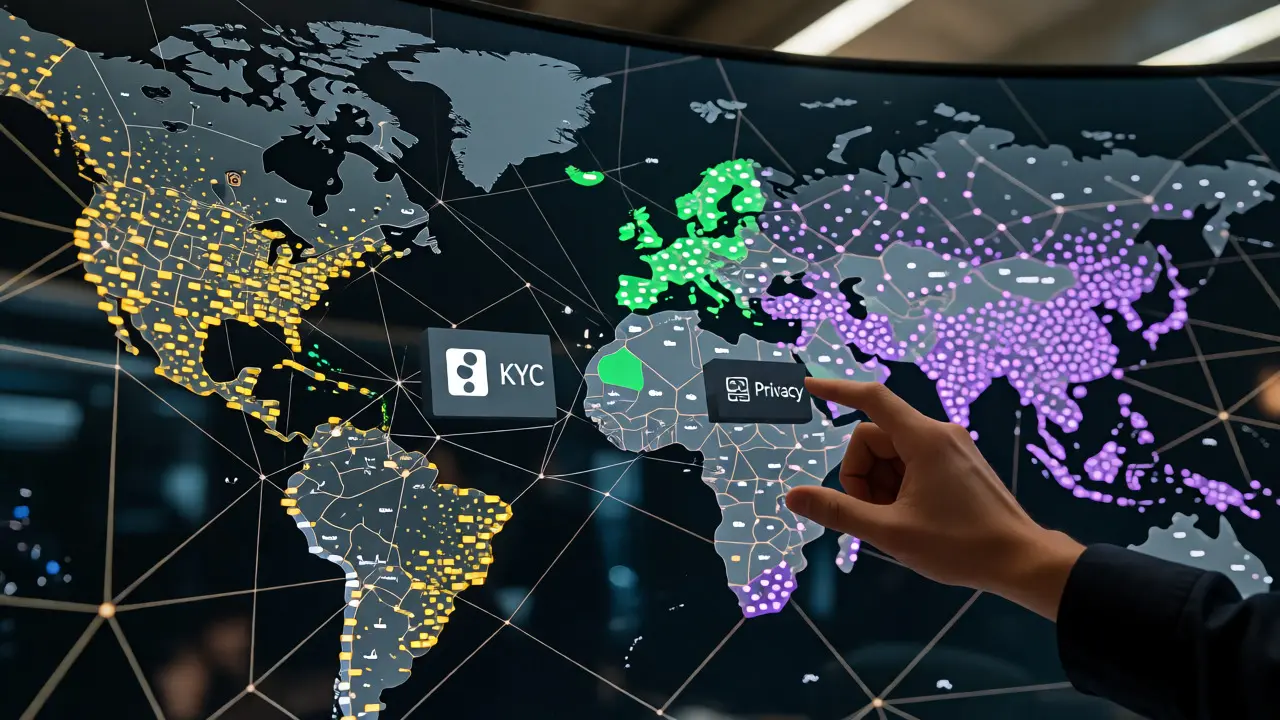
You can’t ignore geography when dealing with DeFi compliance. The European Union’s Markets in Crypto-Assets (MiCA) regulation, effective since late 2024, set a high bar. It requires VASPs to have robust KYC procedures, pushing many protocols to adopt optional verification layers to remain compliant. In contrast, the US remains fragmented. The SEC has filed enforcement actions against platforms deemed insufficiently compliant, creating uncertainty. Vitalik Buterin, co-founder of Ethereum, warned in February 2025 that mandatory KYC at the protocol level undermines DeFi’s value proposition. He argues regulations should target centralized intermediaries, not the code itself.
This divergence forces developers to build modular systems. An app targeting Asian markets might need different compliance checks than one serving US customers. Asia-Pacific is seeing the fastest growth in compliance solutions, up 58% year-over-year, driven by strict local laws. North America leads in absolute market size, but the regulatory environment is less predictable. If you’re building or investing, assume that regional variations will persist through 2027.
Practical Steps for Users and Developers
So, what does this mean for you? If you’re a user, you have choices. Non-custodial wallets like Zengo Wallet use Multi-Party Computation (MPC) to eliminate seed phrases and avoid traditional KYC during setup. You maintain control and privacy. However, moving fiat currency into these wallets often triggers a check at the on-ramp. Be prepared for that step.
For developers, implementing compliance isn’t just about adding a form field. Integrating a provider like Sumsub or Chainalysis takes weeks of development time. A common pitfall is disrupting user experience. Data shows that 39% of users drop off after encountering complex KYC steps. The best practice is to keep basic functions open and gate only specific features-like higher transaction limits or fiat withdrawals-behind verification.
- Start Simple: Use existing middleware tools rather than building custom ZK circuits from scratch unless necessary.
- Test Locally: Regulatory requirements vary wildly. Test your compliance flow against EU and US standards separately.
- Communicate Clearly: Tell users why you’re asking for data. Transparency reduces drop-off rates.
The Future: Modular and Selective Verification
By 2027, Gartner predicts that 75% of DeFi protocols will implement some form of optional KYC infrastructure. The trend is toward modularity. Imagine a future where your digital identity is portable. You verify once with a trusted third party, receive a cryptographic credential, and present it to multiple protocols without sharing raw data. This is the goal of the Decentralized Identity Alliance.
We are also seeing the rise of "compliance-aware" account abstraction on Ethereum. Proposed improvements like EIP-7252 could allow applications to enforce compliance rules at the wallet level without changing the underlying protocol. This keeps the blockchain neutral while letting apps decide how much verification they need. It’s a win-win: regulators get oversight, and users keep their sovereignty.
The market for compliance infrastructure is exploding, projected to hit $42.3 billion by 2028. This isn’t just about avoiding fines; it’s about unlocking liquidity. Institutional capital won’t enter a pool if it can’t trace the source of funds. By offering clear, privacy-respecting compliance paths, DeFi protocols signal maturity. The wild west is closing, but the frontier is still wide open for those who can navigate the new rules.
Do I always need KYC to use DeFi?
No, not always. Many core DeFi functions, such as swapping tokens on decentralized exchanges like Uniswap or providing liquidity, do not require KYC. However, converting fiat currency (like USD or EUR) into crypto usually requires KYC through an on-ramp service. Additionally, some protocols offer premium features or higher limits that may require optional verification.
What are zero-knowledge proofs in the context of KYC?
Zero-knowledge proofs (ZKPs) are cryptographic methods that allow a user to prove they meet certain criteria (e.g., being over 18, not being sanctioned) without revealing their actual identity or personal data. This enables compliance with anti-money laundering (AML) regulations while preserving user privacy, as the verifier doesn't need to see sensitive documents like passports.
How does the EU's MiCA regulation affect DeFi compliance?
The EU's Markets in Crypto-Assets (MiCA) regulation imposes strict KYC and AML requirements on Virtual Asset Service Providers (VASPs). While purely decentralized protocols may fall outside direct scope, any service acting as an intermediary or offering custodial solutions must comply. This has pushed many DeFi platforms to integrate optional KYC layers to ensure they can serve European users legally.
Are no-KYC exchanges safe?
Safety varies. No-KYC exchanges prioritize privacy and accessibility, often using smart contract escrow or peer-to-peer models. However, they may lack the consumer protections offered by regulated entities. Risks include lower liquidity, potential scams, and difficulty recovering funds if something goes wrong. Always research the platform's history and audit status before trading significant amounts.
Can I use my crypto for taxes if I don't do KYC?
Yes, but it's more challenging. Without KYC-linked records, you must meticulously track every transaction manually or via wallet-tracking software. Tax authorities increasingly expect transparency, so failing to report income from no-KYC trades can lead to penalties. Using tools that sync with your wallet addresses helps maintain accurate records even without formal identity verification.
